

MAJORITY: Mobile banking
by MAJORITY USA, LLC
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
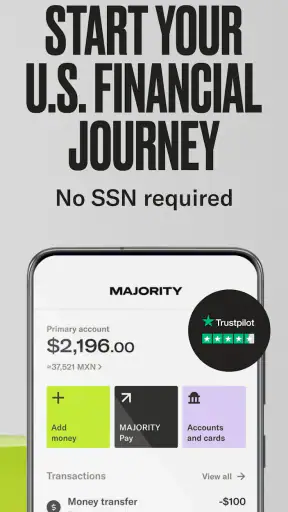
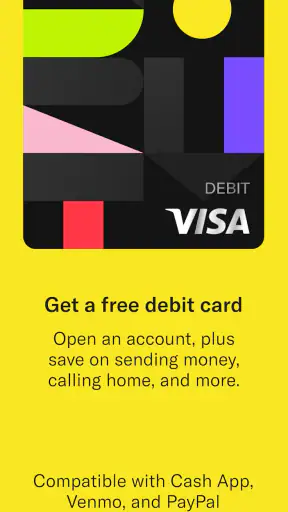
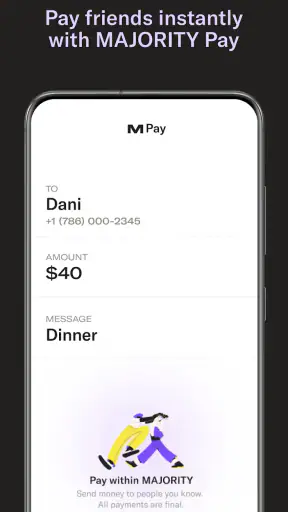
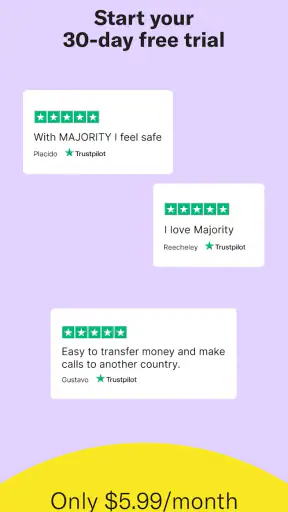
 Analysis by Getfullapps
I came away from MAJORITY seeing it as a practical finance app for people who want a simpler way to manage a US account and debit card, especially when sending money to family abroad is part of everyday life. Its strongest idea is not trying to replace every financial service at once. Instead, it brings several useful tasks into one mobile experience: getting an account, using a card, sending money home, and working toward better credit habits.
That focus makes it easier to understand than a traditional bank app, but it also means it will not suit everyone. I would recommend it most to newcomers to the US, people who regularly support relatives in another country, and users who want a straightforward starting point rather than a complicated banking setup. Someone looking for a full-service bank relationship, advanced savings tools, or a broad investment platform should look elsewhere.
What using MAJORITY feels like in daily life
The app is developed by MAJORITY USA, LLC and belongs firmly in the finance category. It is free to install, rated for Everyone, and has grown to more than a million installs. Its average rating sits at 4.7 from roughly twenty-three thousand ratings, with about twelve thousand written reviews. Those figures suggest that the basic proposition is connecting with a substantial audience, although popularity alone does not remove the need to check whether its particular approach fits your circumstances.
The first thing I noticed is how clearly the product is aimed at access. Its central promise is a US account and debit card without requiring an SSN, alongside tools for sending money home and building credit. That combination speaks to a very specific problem: managing life in the US when ordinary banking requirements can feel like a barrier. Rather than presenting itself as a financial dashboard for experts, MAJORITY keeps the emphasis on useful everyday transactions.
In a realistic scenario, I can imagine using it after moving to the US for work. A user might need a place to receive money, a card for groceries and transport, and a convenient way to send part of a paycheck to family. Keeping those activities together can be less stressful than juggling a separate account, a remittance service, and a credit-building product. The benefit is not just fewer apps; it is having one familiar place to return to when money needs to move.
The debit card angle also makes the service more tangible than an app that only displays balances. A card can become the everyday spending tool, while the app provides the point of control. I found that appealing for someone who wants to check activity frequently without learning the structure of a large conventional bank. The experience is easier to approach when the main questions are simple: what money is available, what has been spent, and what needs to be sent.
A useful bridge for people starting over financially
MAJORITY is at its most convincing when viewed as a bridge. For a person who has arrived in the US and is still building a financial routine, opening a conventional account can involve unfamiliar terminology, documentation, and processes. The advertised no-SSN account option addresses one of the most intimidating parts of that transition. I would still read the account requirements carefully before signing up, but the idea itself is meaningfully different from the standard bank-first experience.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The same applies to the credit-building focus. Building credit is rarely an instant result; it depends on consistent financial behavior and understanding how a product works. I like that the app puts this goal beside spending and money transfers instead of treating it as an unrelated subject. For a new resident, learning to use a debit card responsibly while becoming more aware of credit can be a sensible sequence.
One practical tip is to treat the app as part of a routine rather than a place you open only when something goes wrong. I would check transactions after regular spending, review transfers before confirming them, and keep a separate note of recurring obligations. That habit helps reveal whether the service is actually reducing complexity. If I still needed several other apps to understand my finances, the convenience would be less impressive.
Sending money home is the feature that gives it purpose
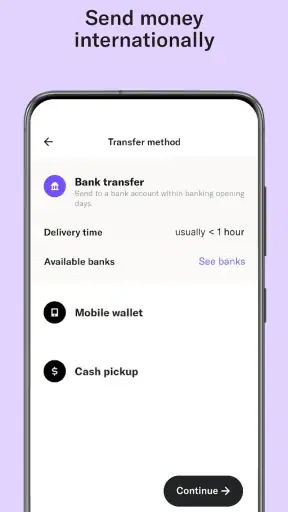
Many finance apps offer accounts and cards, but MAJORITY becomes more distinctive because sending money home is built into its identity. For users supporting relatives in another country, remittances are not an occasional extra; they may be part of the monthly budget. Having that activity close to the account used for daily spending can make planning easier.
I would use a simple workflow: receive or set aside the money intended for family, verify the recipient and transfer details, then send only the amount that will not interfere with rent, food, or transport. The important insight is that convenience should not replace a pause before confirming. A transfer can feel easy precisely because the steps are streamlined, so I would double-check every destination and amount each time rather than relying on memory.
This is also where MAJORITY may be preferable to a normal bank app for a particular audience. A regular bank can be perfectly adequate for domestic payments, but it may not make cross-border family support feel central to the experience. A dedicated remittance service may offer a more specialized workflow, while MAJORITY offers the advantage of keeping the account, card, and sending activity together. The better choice depends on whether simplicity in one app matters more to you than comparing specialized transfer services.
I would not choose any money-transfer product solely because the process feels friendly. Before sending a large amount, I would inspect the final terms shown in the app and compare the result with another established option. Exchange rates, delivery timing, recipient access, and transfer conditions can matter more than a polished interface. That is not a criticism unique to MAJORITY; it is a sensible rule whenever money crosses borders.
Where the experience can become limiting
The same focused design that makes MAJORITY approachable may feel restrictive once your financial life becomes more complex. If you want a broad range of banking products, detailed budgeting categories, investment management, or a highly established branch-based relationship, this is probably not the right primary account. I see it as a focused financial tool, not a universal replacement for every institution a person might use.
The no-SSN positioning is attractive, but it should not be interpreted as “no verification” or “no responsibilities.” Financial services still require users to provide accurate personal information and follow the app’s account-opening process. Anyone considering it should be prepared to read the onboarding screens carefully and understand what access is available to them. The promise removes one familiar obstacle; it does not mean every applicant will have an identical experience.
I also think users should be realistic about the credit-building goal. An app can provide a route or structure, but it cannot substitute for patience, payment discipline, and keeping spending under control. If you are hoping to repair your credit quickly without changing your habits, the product will disappoint you. I would use the credit feature as one part of a longer plan, alongside checking reports, avoiding unnecessary borrowing, and making every required payment on time.
Another limitation is emotional rather than technical: putting daily spending and family transfers in the same place can make the balance look healthier than it really is. Money set aside for a relative is not truly available for casual purchases. My advice is to divide the balance mentally, and if possible in your own records, into spending money, upcoming bills, and money reserved for sending. That small discipline prevents the convenience of a combined account from creating accidental shortfalls.
Who should use it, and who should pass
I think MAJORITY is a strong match for immigrants and newcomers who need a practical US financial starting point. It is also relevant to people who send money to family regularly and would rather avoid maintaining separate tools for domestic card spending and international support. The free price makes it easier to explore, and the Everyone rating makes the basic audience broad, though suitability still depends on personal circumstances and the account process.
It can also work for someone who values a mobile-first experience and wants a debit card connected to a simple account. If your priority is seeing everyday activity in one place and having money-transfer needs close at hand, the app’s focused design is an advantage. I would especially consider it for users who feel overwhelmed by large banking apps filled with features they do not intend to use.
I would be more cautious about recommending it as the only financial home for someone with multiple income sources, complex tax needs, substantial savings goals, or a strong preference for in-person service. A traditional bank may be better for a wider product range and mature account infrastructure. A specialist transfer service may be better if international sending is your only concern and you want to compare transfer-specific conditions closely. A dedicated credit product may be more suitable if credit improvement is your sole objective.
Families should also discuss access and responsibility before sharing financial plans around the app. The convenience of sending money does not remove the need to agree on amounts and timing. I would set a personal monthly limit, keep emergency money separate, and avoid making a transfer simply because a relative asks at the last minute. The app can make the action easier; it cannot decide whether the action is affordable.
Version, longevity, and the overall fit
The current version is 5.14.0 and supports devices running iOS 9 or later. That gives the product a clear place for users who are keeping an older Apple device in service, although I would still keep the operating system and app updated whenever possible for a smoother financial experience. With a release date of April 26, 2019, MAJORITY is not a brand-new experiment; it has had time to develop a recognizable purpose and audience.
That history matters to me because financial apps need to feel dependable over repeated use, not merely impressive during the first five minutes. I would judge it by whether account access, card use, and transfers fit naturally into my weekly routine. The high average rating and sizeable user base are encouraging signs, but my own decision would still come down to the specific needs of having a US account, sending money home, and working on credit in one place.
One useful way to test the fit is to start with low-risk tasks. I would explore the account screens, understand how the debit card is managed, and become comfortable reviewing activity before relying on it for an important family transfer. This staged approach is better than moving every financial responsibility immediately. It also gives you a chance to compare the app’s workflow with your current bank or remittance provider without making a rushed switch.
My final recommendation
After looking at the app as a complete everyday tool, I see MAJORITY as a focused solution with a clear audience rather than a universal banking replacement. Its best qualities are the combination of a US account and debit card, access designed around people without an SSN, money transfers to family, and a credit-building direction. Those pieces make sense together, especially for someone establishing a life in the US while staying financially connected to relatives elsewhere.
Its weaknesses are equally important. Users with advanced banking needs may outgrow the focused approach, and anyone expecting effortless credit improvement will need to adjust their expectations. I would also compare transfer details before sending significant amounts and keep careful boundaries between everyday spending and money reserved for family.
For the right person, that is a worthwhile trade-off. If you want a free, mobile-centered finance app built around access, a debit card, family remittances, and a gradual financial start, I think MAJORITY deserves a serious look. If you already have a complete bank setup and need sophisticated financial planning, I would keep your existing institution and use a more specialized service where necessary. My verdict is positive, but specific: choose it for its focused bridge between US daily banking and supporting family abroad, not because it promises to replace every financial service you use.
Pros
- Simple mobile banking tools for checking balances and managing money
- Convenient access to account information from a smartphone
- Useful features for tracking everyday spending and transactions
- Designed with accessibility in mind for a broad range of users
- Can reduce the need to visit a physical bank branch
Cons
- Availability and features may depend on your country or supported bank
- Some services may require identity verification before full access
- Mobile banking depends on a stable internet connection
- Not all account types or banking products may be supported
- Users should review fees and terms for optional financial services
FAQs for MAJORITY: Mobile banking
What is MAJORITY: Mobile banking, and who is it designed for?
MAJORITY is a mobile banking and financial services app aimed primarily at immigrants, newcomers, and people who need a convenient way to manage everyday money across the United States. The app typically combines features such as a spending account, debit card access, money transfers, international remittances, and communication tools. Availability, eligibility, and included services can depend on your location and the current subscription terms.
Do I need to pay a monthly fee to use MAJORITY?
MAJORITY generally operates through a membership or subscription model rather than offering every feature completely free of charge. Before signing up, review the current monthly price, trial conditions, renewal policy, and any additional charges shown in the app. Fees may vary by plan or promotion, and services such as international transfers, ATM usage, card replacement, or expedited transactions may have separate limitations or costs.
Can I send money internationally with MAJORITY?
One of MAJORITY’s main attractions is its support for international money transfers, particularly for users sending funds to family members abroad. However, supported countries, delivery methods, exchange rates, transfer limits, processing times, and fees can change. Before confirming a transaction, carefully check the recipient information, the amount they will receive, and the total cost displayed in the app.
Is MAJORITY a bank, and is my money protected?
MAJORITY provides financial services through banking partners and should not automatically be understood as a traditional bank in every respect. Account features, deposit arrangements, and applicable protections depend on the partner institutions and the specific product being used. Read the account agreement and disclosures inside the app to understand eligibility, transaction limits, dispute procedures, and whether applicable deposit insurance covers your funds.
What documents are required to open a MAJORITY account?
During registration, MAJORITY may request personal information and identity documents to comply with financial regulations and verify your account. Requirements can include your legal name, date of birth, address, phone number, government-issued identification, and possibly immigration or tax-related information depending on your circumstances. Make sure the details are accurate, use a secure connection, and only submit documents through the official application.

MAJORITY: Mobile banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@majority.com, visit https://www.majority.com, or review their https://www.majority.com/en/terms-of-use/privacy-policy/.










